The Risk of Waiting
For many independent insurance brokerages, the question is no longer whether they will eventually sell or partner—it’s when. But some firms wait too long.
Many growth-focused independent insurance brokers recognize they may need to sell or partner in the future to maintain their long-term growth trajectory.
Yet, despite a robust M&A environment, many are waiting. Owners often assume there will be a better time, a stronger market, or a higher valuation opportunity down the road. That assumption carries risk.
Many firms have historically outperformed the market, delivering strong organic growth, attracting talented producers, and building respected leadership teams. For years, these firms appeared to be ideal acquisition candidates. Yet they didn’t sell for one reason or another. Then, gradually, momentum slowed. Investment in talent, technology, or business development was deprioritized. Some firms benefited from favorable market conditions and grew complacent with the hard market. Over time, key producers departed, important accounts were lost, and organic growth rates declined.
But buyers place significant value on future performance, not just historical success. A firm that once stood among the industry’s top performers may still have strong leadership, talented people, and an attractive client base. However, if growth stalls or competitive challenges become more visible, buyer interest may become more selective and valuations may come under pressure.
That does not mean opportunities disappear. Far from it.
Quality firms are still attracting meaningful interest across the marketplace. Healthy fundamentals, accomplished teams, and disciplined management remain highly desired. However, as market conditions soften, the gap between top-performing and average firms is continuing to widen. Organizations that continue to invest in talent and technology, maintain strong sales velocity, and generate significant organic growth will distinguish themselves from competitors that simply hold steady.
This leaves an important strategic question for owners who anticipate making a partnership or sales decision within the next three to five years: what are the risks of waiting?
Remaining independent carries meaningful benefits, including maintaining control, preserving company culture, and retaining strategic flexibility. However, those advantages must be weighed against the realities of a changing marketplace. If growth becomes more difficult, talent retention becomes more challenging, and competitive pressures increase, is your organization likely to improve its position or lose ground?
In a tough market, standing still is often viewed as underperformance. For agency owners considering a future transaction, the greatest risk may not be selling too early. It may be waiting until the market is already telling a different story about the value of their business.
Remaining independent carries meaningful benefits, including maintaining control, preserving company culture, and retaining strategic flexibility. However, those advantages must be weighed against the realities of a changing marketplace.
M&A Market Update
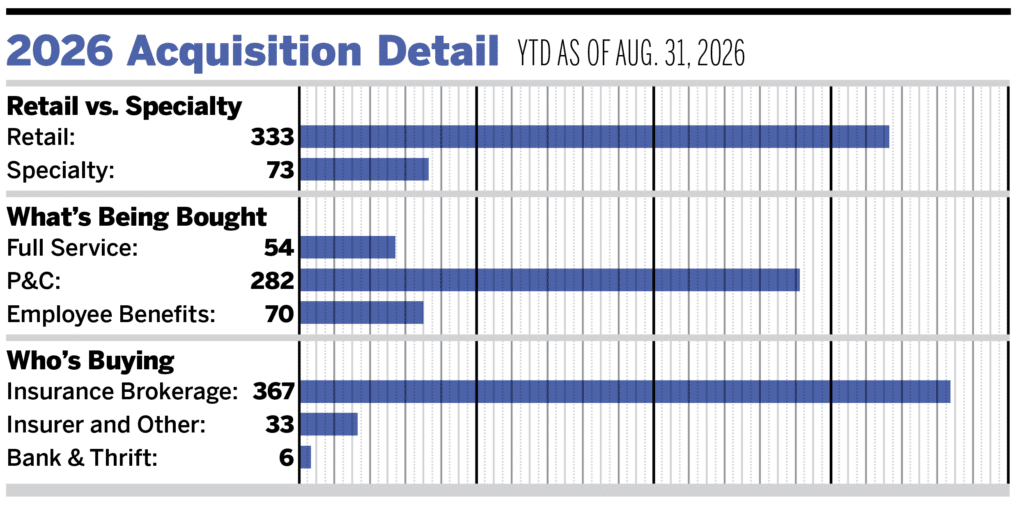
As of Aug. 31, there were 406 announced insurance brokerage M&A transactions in the United States in 2026—down 7.4% from 436 deals last year at this time. Private capital-backed buyers accounted for 305 of the 406 deals (75.1%) through July.
Independent brokers’ share of deal activity has steadily declined over the years, mostly due to private equity’s scaled and sustained increase in M&A. Through August, independent acquirers accounted for 33 transactions, representing 8.1% of the market, while bank buyers have announced six transactions to date this year. Deals involving specialty intermediaries as targets accounted for 73 transactions, representing 18.0% of all acquisitions.
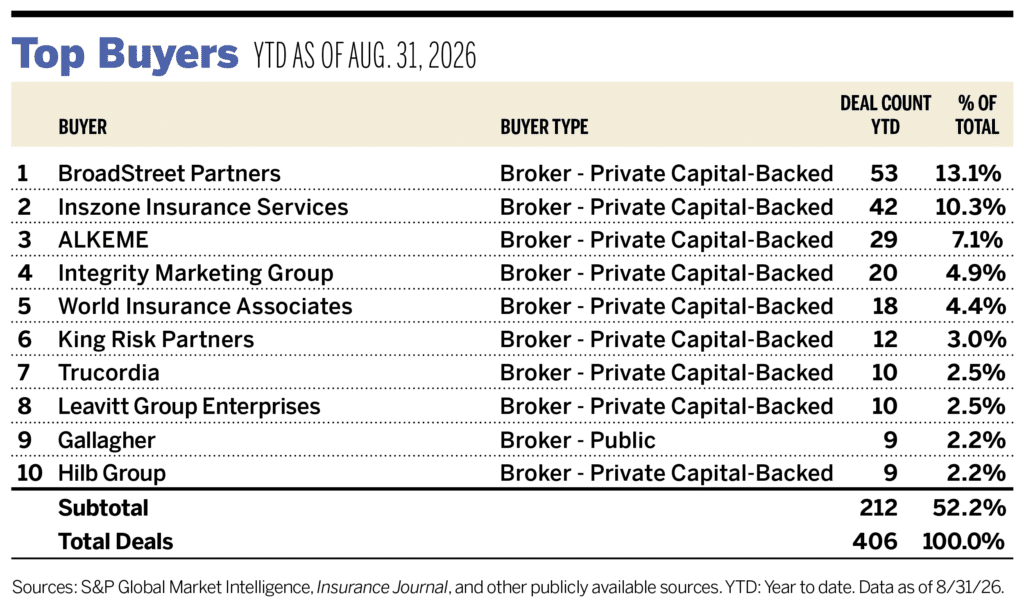
Ten buyers accounted for 52.2% of all announced transactions year to date, while the top three (BroadStreet Partners, Inszone, and ALKEME) represented 30.5% of the 406 deals.
Notable Transactions
- Aug. 12: Sunstar Insurance Group acquired RJR Faribo Insurance Agency, an independent Minnesota brokerage, marking Sunstar’s entry into the state and expanding its Midwest presence. The partnership provides RJR Faribo with access to broader carrier relationships and specialized capabilities while preserving its local leadership, team, and client relationships. MarshBerry advised RJR Faribo in this transaction.
- Aug. 31: Aon agreed to acquire USI Insurance Services from KKR and other shareholders for $17.0 billion, significantly expanding its position in the U.S. middle-market insurance brokerage sector following the acquisition of NFP in 2024. USI is the 10th-largest U.S. insurance brokerage, with more than 10,500 employees across nearly 200 offices. The deal is expected to close before the end of 2026.