An Insurance Exchange’s Wild Ride
MGA Accelerant’s journey from 55x growth story to 12x buyout target.
Accelerant is a specialty insurance platform connecting MGAs with capital partners through a proprietary, data-driven risk exchange.
Rather than just another AI play on insurance, Accelerant is the real deal: the exchange ran $1.3 billion of premium in the first half of this year alone. To us, Accelerant represents the future of specialty insurance distribution.
An EBITDA Ladder
Getting here has been a wild ride, and adjusted EBITDA multiples tell the story better than dollars alone. Accelerant went public on July 24, 2025, at $21 per share, valuing the company at about 42x trailing adjusted EBITDA. Investors kept buying shares, which closed as high as $30.05 on Aug. 22, 2025, pushing the multiple to north of 55x that same trailing adjusted EBITDA base.
Then came the reversal. Accelerant’s stock, like much of the insurance distribution sector, got swept up in the AI insurance scare that hit broker stocks in February 2026, after a ChatGPT-powered rate-comparison tool from Insurify spooked the market (WTW fell 12% and Gallagher nearly 10% in a single session). Accelerant kept sliding in the following months, eventually touching a low of just 7x trailing adjusted EBITDA, a fraction of where it started.
| Stage | Date | Share Price | Implied Enterprise Value | Trailing 12 Month Adjusted EBITDA | Enterprise Value/Adjusted EBITDA |
| IPO | Jul. 24, 2025 | $21.00 | ~$4.7B | $112.8M (FY 2024) | ~42x |
| Peak | Aug. 22, 2025 | $30.05 | ~$6.4B | $112.8M (FY 2024) | ~55x+ |
| Trough | Feb. 24, 2026 | $9.18 | ~$2.0B | $281.8M (FY 2025) | ~7x |
| Thoma Bravo Deal | Aug. 13, 2026 | $20.25 | >$4.0B | $338.6M | ~11.8x |
Remarkably, this drop happened while the business kept compounding. Adjusted EBITDA nearly tripled, from $112.8 million in fiscal 2024, to $281.8 million in fiscal 2025, to $338.6 million on a trailing-12-month basis through the second quarter of 2026. Exchange written premium reached $1.3 billion in the first half of 2026, up 23% year over year. In short, the multiple the market was willing to pay collapsed even as the underlying numbers improved dramatically.
Thoma Bravo Steps In
Thoma Bravo, the $172 billion software-focused private equity firm famous for its technology bets, is not a business we typically see in the specialty insurance market. Yet on Aug.13, 2026, it agreed to take Accelerant Holdings private in an all-cash deal valuing the specialty insurance platform at more than $4 billion in enterprise value, with shareholders receiving $20.25 per share. This valuation represents a nearly 50% premium on the $13.61 closing price the day before the deal, or a value that circles right back to its IPO price a little over a year earlier, except adjusted EBITDA has nearly tripled since the IPO. Effectively, Thoma Bravo bought the business at roughly 12x trailing adjusted EBITDA, a fraction of the roughly 42x trailing adjusted EBITDA the company went public at, though still an improvement over the roughly 7x trailing adjusted EBITDA the stock touched at its low.
The deal reads two ways at once. Thoma Bravo is best known as a technology buyer, and Accelerant’s proprietary underwriting and pricing software fits that mold. But functionally, Accelerant also operates as an MGA-style distribution platform, which puts the deal squarely in specialty insurance M&A and extends Thoma Bravo’s push into insurance technology; its Nearmap subsidiary previously acquired property claims-technology firm itel for more than $1.3 billion.
Altamont Capital Partners, which controls roughly 82% of outstanding Accelerant stock, has agreed to vote in favor of the deal; along with the company’s founders, it will retain equity alongside Thoma Bravo after closing. The sale is expected to close in the first half of 2027.
Peer Comparison
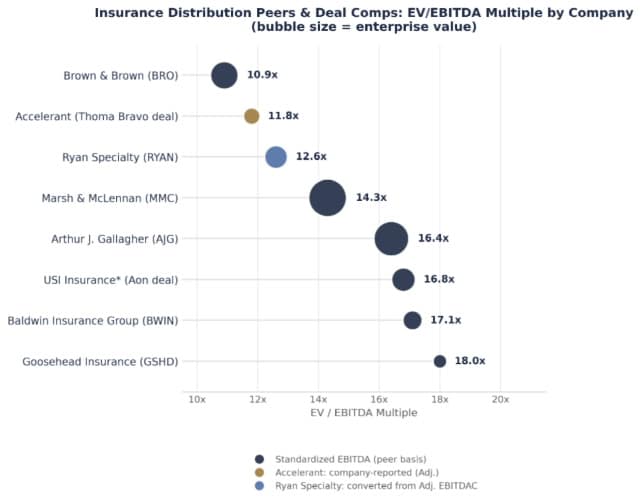
Ryan Specialty Group is the closest direct public comparison to Accelerant, a specialty and wholesale insurance distribution platform that has followed a similar high-growth path off a much larger revenue base. It reports on its own non-GAAP metric, adjusted EBITDAC (which adds back interest, taxes, depreciation, amortization, and change in contingent consideration, plus stock compensation and certain other items). Adjusted EBITDAC was $811.2 million in fiscal 2024, growing 19.2% to $966.7 million in fiscal 2025 at a 31.7% margin. Growth continued into 2026: Q2 2026 adjusted EBITDAC was $326.9 million (up 6% year over year, 35.7% margin) and first-half 2026 adjusted EBITDAC was $558.9 million (up 9.8% year over year, 32.7% margin), with margin growth moderating on higher compensation costs. Converted to the standard EBITDA basis used for market comparisons, Ryan Specialty currently trades at approximately 12.6x EV/EBITDA (about $14.6 billion EV on about $1.16 billion TTM EBITDA, as of Aug. 31, 2026).
Widening the comparison set beyond Ryan Specialty to five more publicly traded insurance distribution platforms puts peer EV/EBITDA multiples in a 10.8x to 18.0x range, averaging about 14.3x with a median of about 14.5x. Thoma Bravo’s implied roughly 11.8x multiple for Accelerant sits in the lower half of that range: above the two large, diversified brokers (Brown & Brown and Marsh & McLennan, both around 10.8x to 10.9x), but below Ryan Specialty and the higher-growth, more specialty-concentrated names (Gallagher, Goosehead, and Baldwin, all 16x to 18x), and below the peer set’s average and median overall.
For a live read on the market: Aon’s pending $17 billion acquisition from KKR and other owners of USI Insurance Services, a non-specialty, middle-market broker, is priced at roughly 16.8x trailing EBITDA.